Stop VAT identity theft and joint fraud liability on cross-border shipments.
Wholesale distributors ship high-value consignments across European borders under Article 138 intra-Community exemptions. When fraudulent buyers hijack legitimate corporate VAT numbers to take delivery without tax, sellers face joint and several liability for missing trader fraud under CJEU case law.
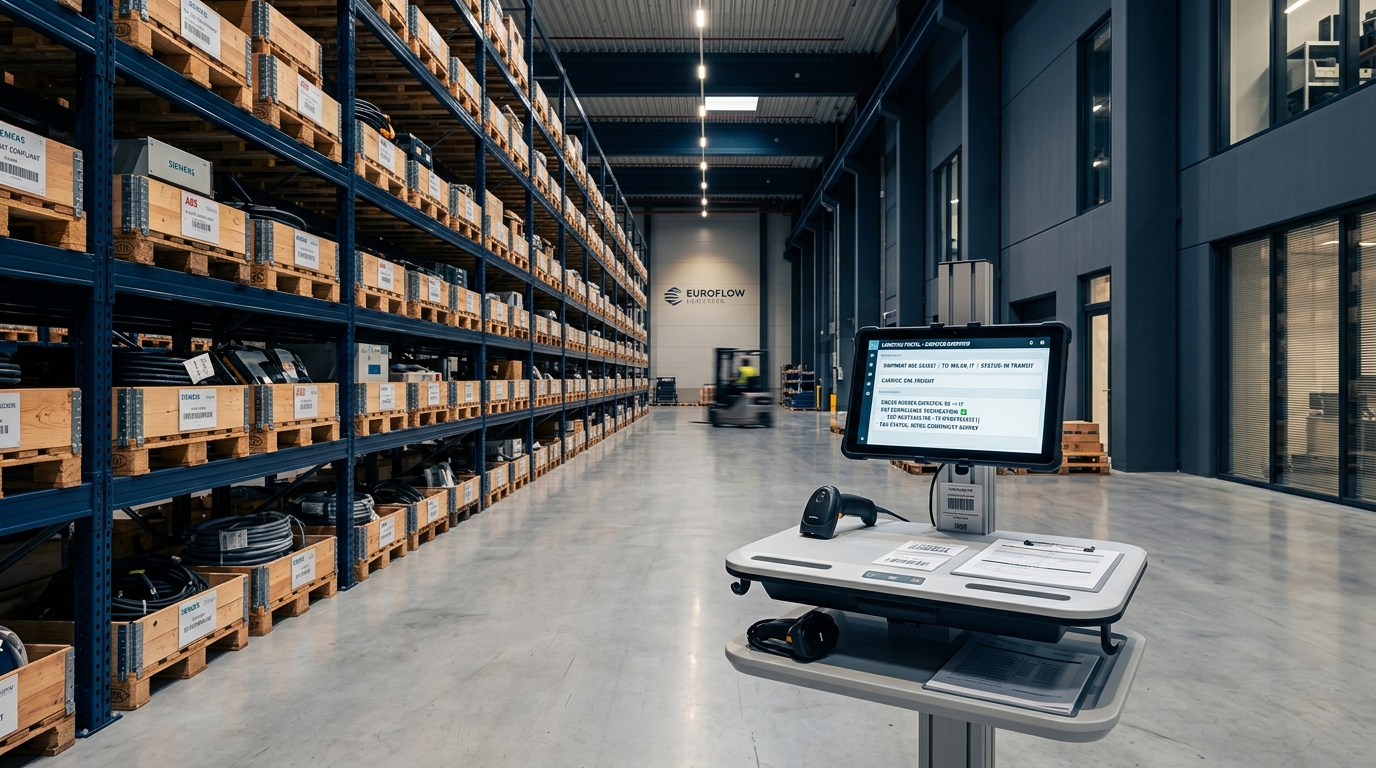
The Missing Trader and VAT Hijacking Trap
In physical wholesale distribution, orders range from €10,000 to over €100,000. Bad actors obtain real VAT numbers belonging to reputable corporations and submit them during order entry. Basic format checkers return valid, and the distributor dispatches goods at zero percent VAT. When tax authorities trace the shipment to an unrelated drop address, the seller is held liable for the unpaid tax.
- Imposters submit valid third-party VAT identifiers to purchase high-value goods without paying domestic tax.
- Basic validation tools confirm that a VAT number exists, but fail to check whether the buyer entity actually owns that identifier.
- Tax authorities invoke joint liability under CJEU Mecsek-Gabona (Case C-273/11) and German UStG Section 25d, assessing uncollected tax directly against the supplier.
Dual Legal Entity Verification and Transport Evidence
VAT.tools verifies both the tax registration and the underlying corporate identity in national commercial registers. Dispatch teams receive verified registered office addresses and official consultation proofs to link directly with CMR transport files.
- Dual-Layer Identity Check
Query national company registers alongside tax databases to confirm that the ordering entity legally owns the specified VAT registration.
- Registered Address Verification
Compare the customer delivery destination against the registered corporate office on file, flagging address diversions before shipping.
- CMR Transport File Attachment
Generate time-stamped proof receipts with official authority consultation numbers to archive alongside bills of lading and transport proofs.
Source Provenance and Evidence Discipline
VAT.tools never guesses. Every check queries certified official registers and tax authorities, returning an immutable verification record with source timestamps and legal citations attached.
Dual-Layer Identity Check
Query national company registers alongside tax databases to confirm that the ordering entity legally owns the specified VAT registration.
Registered Address Verification
Compare the customer delivery destination against the registered corporate office on file, flagging address diversions before shipping.
CMR Transport File Attachment
Generate time-stamped proof receipts with official authority consultation numbers to archive alongside bills of lading and transport proofs.
Statutory and Regulatory Basis
The European directives, court decisions, and national laws governing this workflow.
Ready to eliminate European tax complexity?
Create an organization account and start verifying counterparties in sandbox or live environments.